In real estate debt investing, if someone tells you a lender received a large check, the next question should be pretty simple: how much of that check was the lender’s own money coming back?
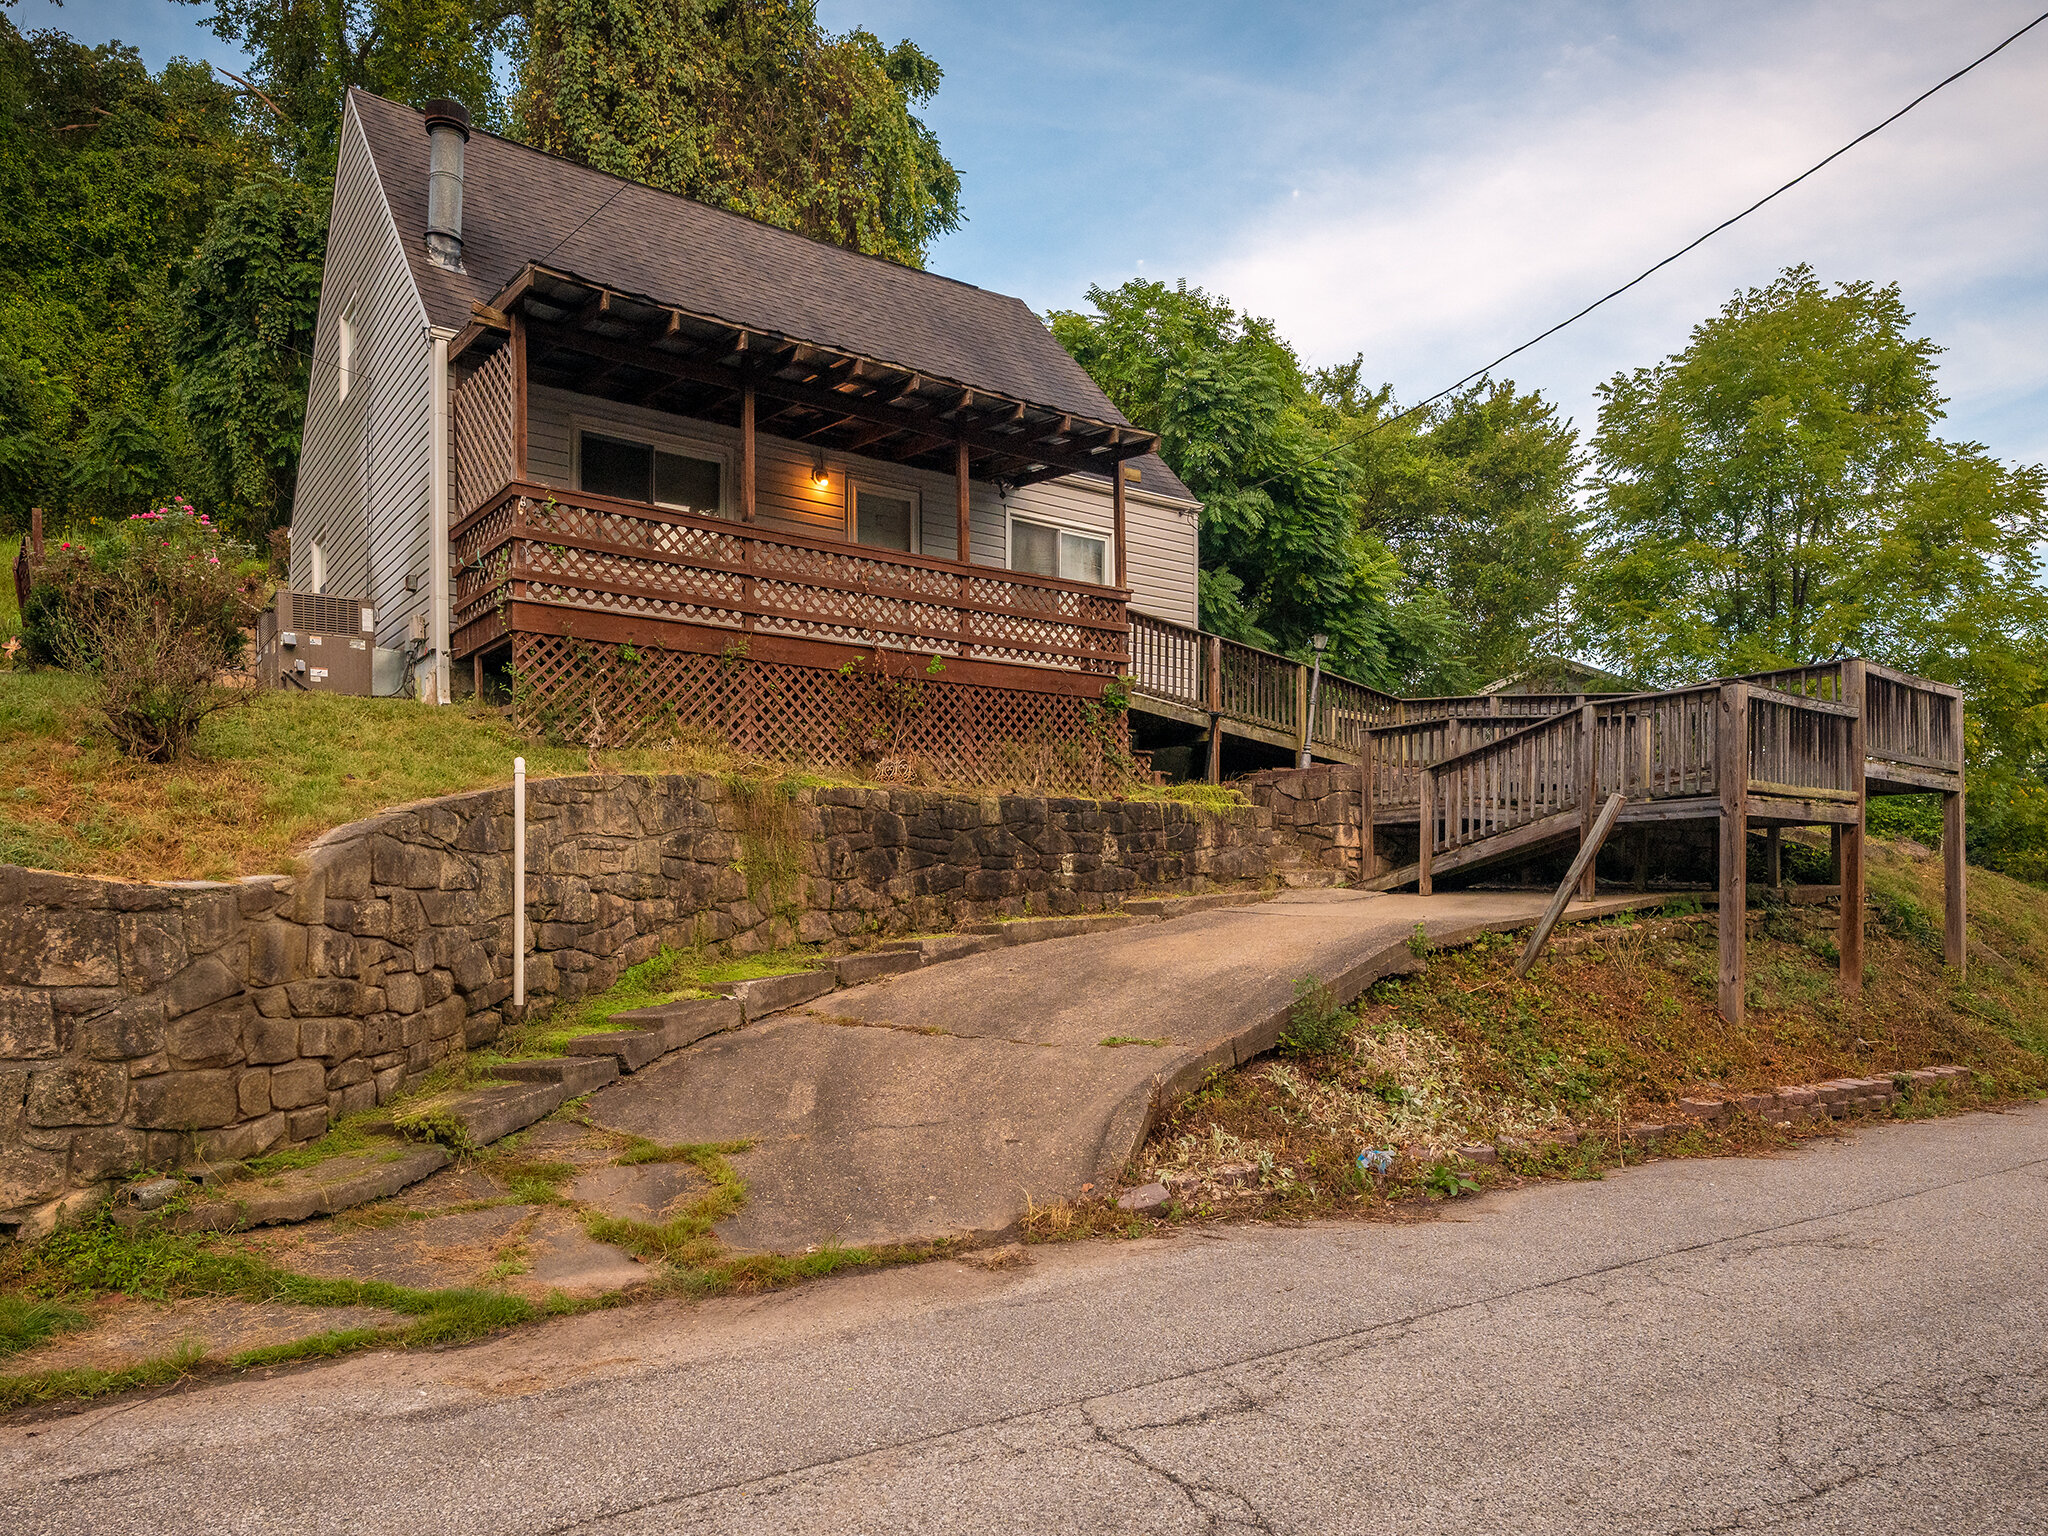
Principal repayment and interest are different things. Understanding that difference is a good starting point for evaluating real estate debt investing. Our completed King Street project in South Charleston gives us a straightforward example.
Historical loan summary
| Actual principal advanced | $37,368.05 total; initial advance $27,503.93 |
|---|---|
| Contractual annual rate | 10% per year |
| Initial funding to sale closing | 84 days — July 17 to October 9, 2026 |
| Interest in closing payoff | $1,500.00 |
Timing and calculation note: Additional advances occurred after the initial funding date, so the full $37,368.05 was not outstanding for all 84 days. The signed note allowed up to $120,000; that was not the amount actually advanced. The draw-by-draw interest calculation has not been reconciled.
The annual rate is a contract term, not the return earned over the displayed period. Funding-to-closing is not the time to confirmed lender receipt. Actual received or bank-cleared payoff dates have not been independently verified. Interest shown is the closing-payoff allocation identified in company records, before any tax or lender expenses. These selected historical examples do not promise future results.
What the King Street records show
The property sold on October 9, 2026. The closing statement allocated $38,868.05 to a mortgage payoff. Our company report identifies that total as $37,368.05 in principal and $1,500 in interest and reports that the lender was paid back at closing.
The $38,868.05 wasn’t all income. Most of it was the return of money advanced to the project. The reported interest component was $1,500.
The closing statement copy reviewed for this example is an unsigned extract, and the later company report supports the payoff breakdown. That distinction matters: these records aren’t an independent confirmation of the date funds cleared in the lender’s bank account. We aren’t presenting the example as a complete payment audit.
King Street is a sold project, not a current property or lending opportunity. Its reported interest amount is a historical result for that loan, not a typical return or a forecast.
Reading returns in real estate debt investing
To understand a loan’s return, you also need to know how much money was outstanding and for how long. A project funded in several advances can have a different cash-flow pattern from one funded entirely on the first day.
You also need to separate agreed interest, any fees, the amount allocated at closing and the amount actually received. Those numbers may relate to one another, but they aren’t interchangeable.
For King Street, we’re using the documented principal and interest breakdown. We aren’t converting the $1,500 into an annualized yield because the full draw schedule and interest calculation haven’t been reconciled for that purpose. A precise-looking percentage wouldn’t make the example more useful if it suggested more certainty than the records support.
Follow the repayment all the way through
A loan review shouldn’t end with the projected sale date. Before funding, ask who prepares the payoff, how the amount is checked and how repayment will be delivered. After a sale, distinguish a closing allocation from a disbursement and from confirmed receipt.
A mailed check can arrive after closing. A payoff can include interest through a particular date. A delay may require a revised calculation. Keeping those steps separate makes it easier to understand what happened and resolve questions without confusing principal, income and timing.
Ask what reporting you’ll receive during the project, too. A lender should understand the planned exit and what happens if the house doesn’t sell when expected. More time on the market can bring additional holding costs and pressure on the project’s finances.
Our document checklist for real estate debt investing covers the separate questions of the repayment obligation, collateral and professional review.
A fixed rate still carries risk
A written obligation to pay interest doesn’t ensure the borrower will be able to pay it. The property could sell for less than expected, repairs could cost more, or repayment could be delayed. Collateral may be insufficient, and collecting through legal proceedings can be expensive.
FINRA explains promissory-note risks in real estate debt investing, including the danger of treating a stated rate as a guaranteed outcome. Your own advisers can help you assess the borrower, documents and risks before you make a decision.
At AM Investments, we borrow private funds for some property projects. We don’t offer hard-money loans to buyers. Our company page explains more about the work behind these examples.
For us, the useful way to discuss a lender payoff is to be clear about each part: the principal returned, the interest reported and what the available records establish. That gives you a better basis for asking questions than a headline number on its own.
This is a selected historical example for general education, not an investment offer or a promise of future results. Private real estate debt can involve delays and loss of principal and interest.
